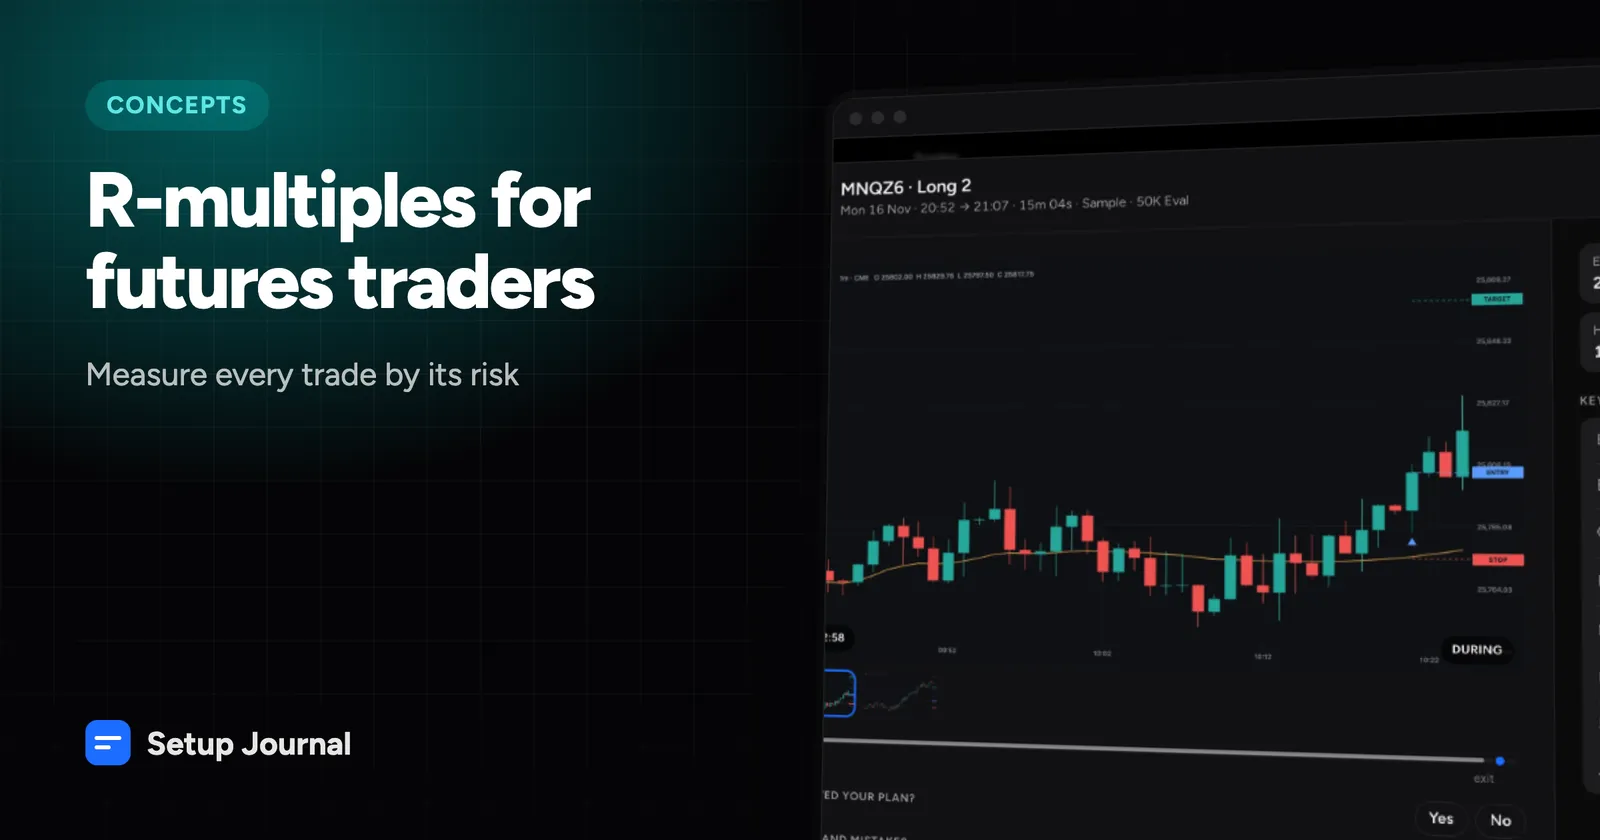
R-multiples for futures traders: measure every trade by its risk
What 1R means, how to calculate the R-multiple of a futures trade, worked examples on MNQ and MES, and why moving your stop quietly breaks it.
· 2 min read
A $200 win means something very different if you risked $50 to make it than if you risked $800. R-multiples measure every trade in units of what you risked. That makes results comparable across contracts, position sizes and account sizes.
What 1R is
1R is the amount you planned to lose on a trade: the distance from your entry to your stop, in money.
1R = |entry − stop| × point value × contracts
Then:
R-multiple = net P&L ÷ 1R
A trade that makes twice what you risked is +2R. A trade stopped out where you planned is −1R.
Worked examples
MNQ long, 2 contracts. MNQ is worth $2 per point.
- Entry 21,450.00, stop 21,437.50: a 12.5-point stop.
- 1R = 12.5 × $2 × 2 = $50.
- Exited at 21,490.00 for +40 points: +40 × $2 × 2 = +$160, minus $3.76 fees = +$156.24.
- R-multiple = 156.24 ÷ 50 = +3.1R.
MES short, 3 contracts. MES is worth $5 per point.
- Entry 6,020.00, stop 6,024.00: a 4-point stop.
- 1R = 4 × $5 × 3 = $60.
- Stopped out at 6,024.25 after a tick of slippage: −4.25 × $5 × 3 = −$63.75, minus fees $5.64 = −$69.39.
- R-multiple = −69.39 ÷ 60 = −1.16R.
Losing a bit more than 1R on a stop is normal: fees and slippage. Losing 2R on a trade that had a stop is not.
Why R beats dollars
- Size changes don’t distort your stats. A trader who goes from 2 to 6 contracts triples their dollar results, but their R-multiples stay comparable.
- Contracts are comparable. A +2R MES trade and a +2R CL trade were equally good trades.
- Expectancy in R is the cleanest measure of an edge. If your average trade is +0.3R, you know what a week of 20 trades should look like at any size.
The stop-moving problem
R only works if 1R is the stop you set at entry. Here’s what happens when it isn’t.
You go long MNQ 2 contracts with a 14.5-point stop: 1R = $58. Price goes against you. Before it hits your stop, you drag the stop another 14.5 points lower “to give it room”. It hits that one instead.
- Loss: 29 points × $2 × 2 = $116, plus fees.
- If you measure R against the moved stop, the trade looks like a disciplined −1R.
- Against the original stop, it was −2R.
The second number is the truth, and a pattern of −2R losses is the single most common reason traders with good setups lose money. That’s why it’s worth tagging “moved stop” as a mistake every time it happens, and comparing your losers to your planned risk.
Getting R without a calculator
To calculate R you need your stop. On Tradovate, your stop orders are in the Orders export, including the price they were filled or canceled at. Setup Journal reads that file, takes the stop for each trade, and shows its risk and R-multiple. You can also type a stop on any trade yourself. Tag the moved-stop trades as you review, and the Setups page shows exactly what that habit costs.